
SELF-EMPLOYED HOME LOANS BRISBANE SOUTHSIDE
A home loan that reads your business the way you run it.
Sole traders, contractors and business owners get assessed off a checklist built for payslips. We place your loan with one of our 50+ lenders whose policy reads self-employed income properly.
Francesco Mercati
“Gundeep was FANTASTIC in getting me across the line on my first home, can't recommend him more!! Chat to us here.
Evergreen is here to help with your Self Employed Home Loan.
Welcome to Evergreen Loan Solutions, where we are dedicated to empowering individuals and families to achieve their Self Employed Home Loan goals with confidence and clarity. Established with a vision to provide personalised financial solutions, Evergreen Loan Solutions has been a trusted partner for clients seeking tailored guidance in navigating the complexities of the financial landscape.
Our Story.
Led by Gundeep Virk, a seasoned banking professional with over 15 years of experience in various roles including home loans, unsecured loans, agri-banking, and branch leadership, Evergreen Loan Solutions is dedicated to providing personalised financial solutions.
Our team take the time to listen and tailor our services to you, providing expert guidance every step of the way.
1. Add-backs that actually get counted.
Depreciation, one-off expenses and super above the minimum can lift your assessable income. We know which lenders recognise which add-backs.
2. Low doc and alt doc options.
Trading under two years, or returns that lag your real position? BAS, an accountant's declaration or business bank statements can stand in for full tax returns.
3. Presented so the right income counts.
We package your financials the way each lender wants to see them, so the income that should count actually does.
Let us research 50+ banks & lenders to find the right solution for you.
We work with Australia’s leading banks and non-bank lenders including ANZ, Bank of Queensland Suncorp, AMP, Macquarie Bankwest and many more, giving you more options, better rates, and loans tailored to your exact needs. No bias, just what works best for you.
How our Brisbane Southside mortgage broker helps
Why do self-employed Brisbane Southside borrowers use Evergreen?
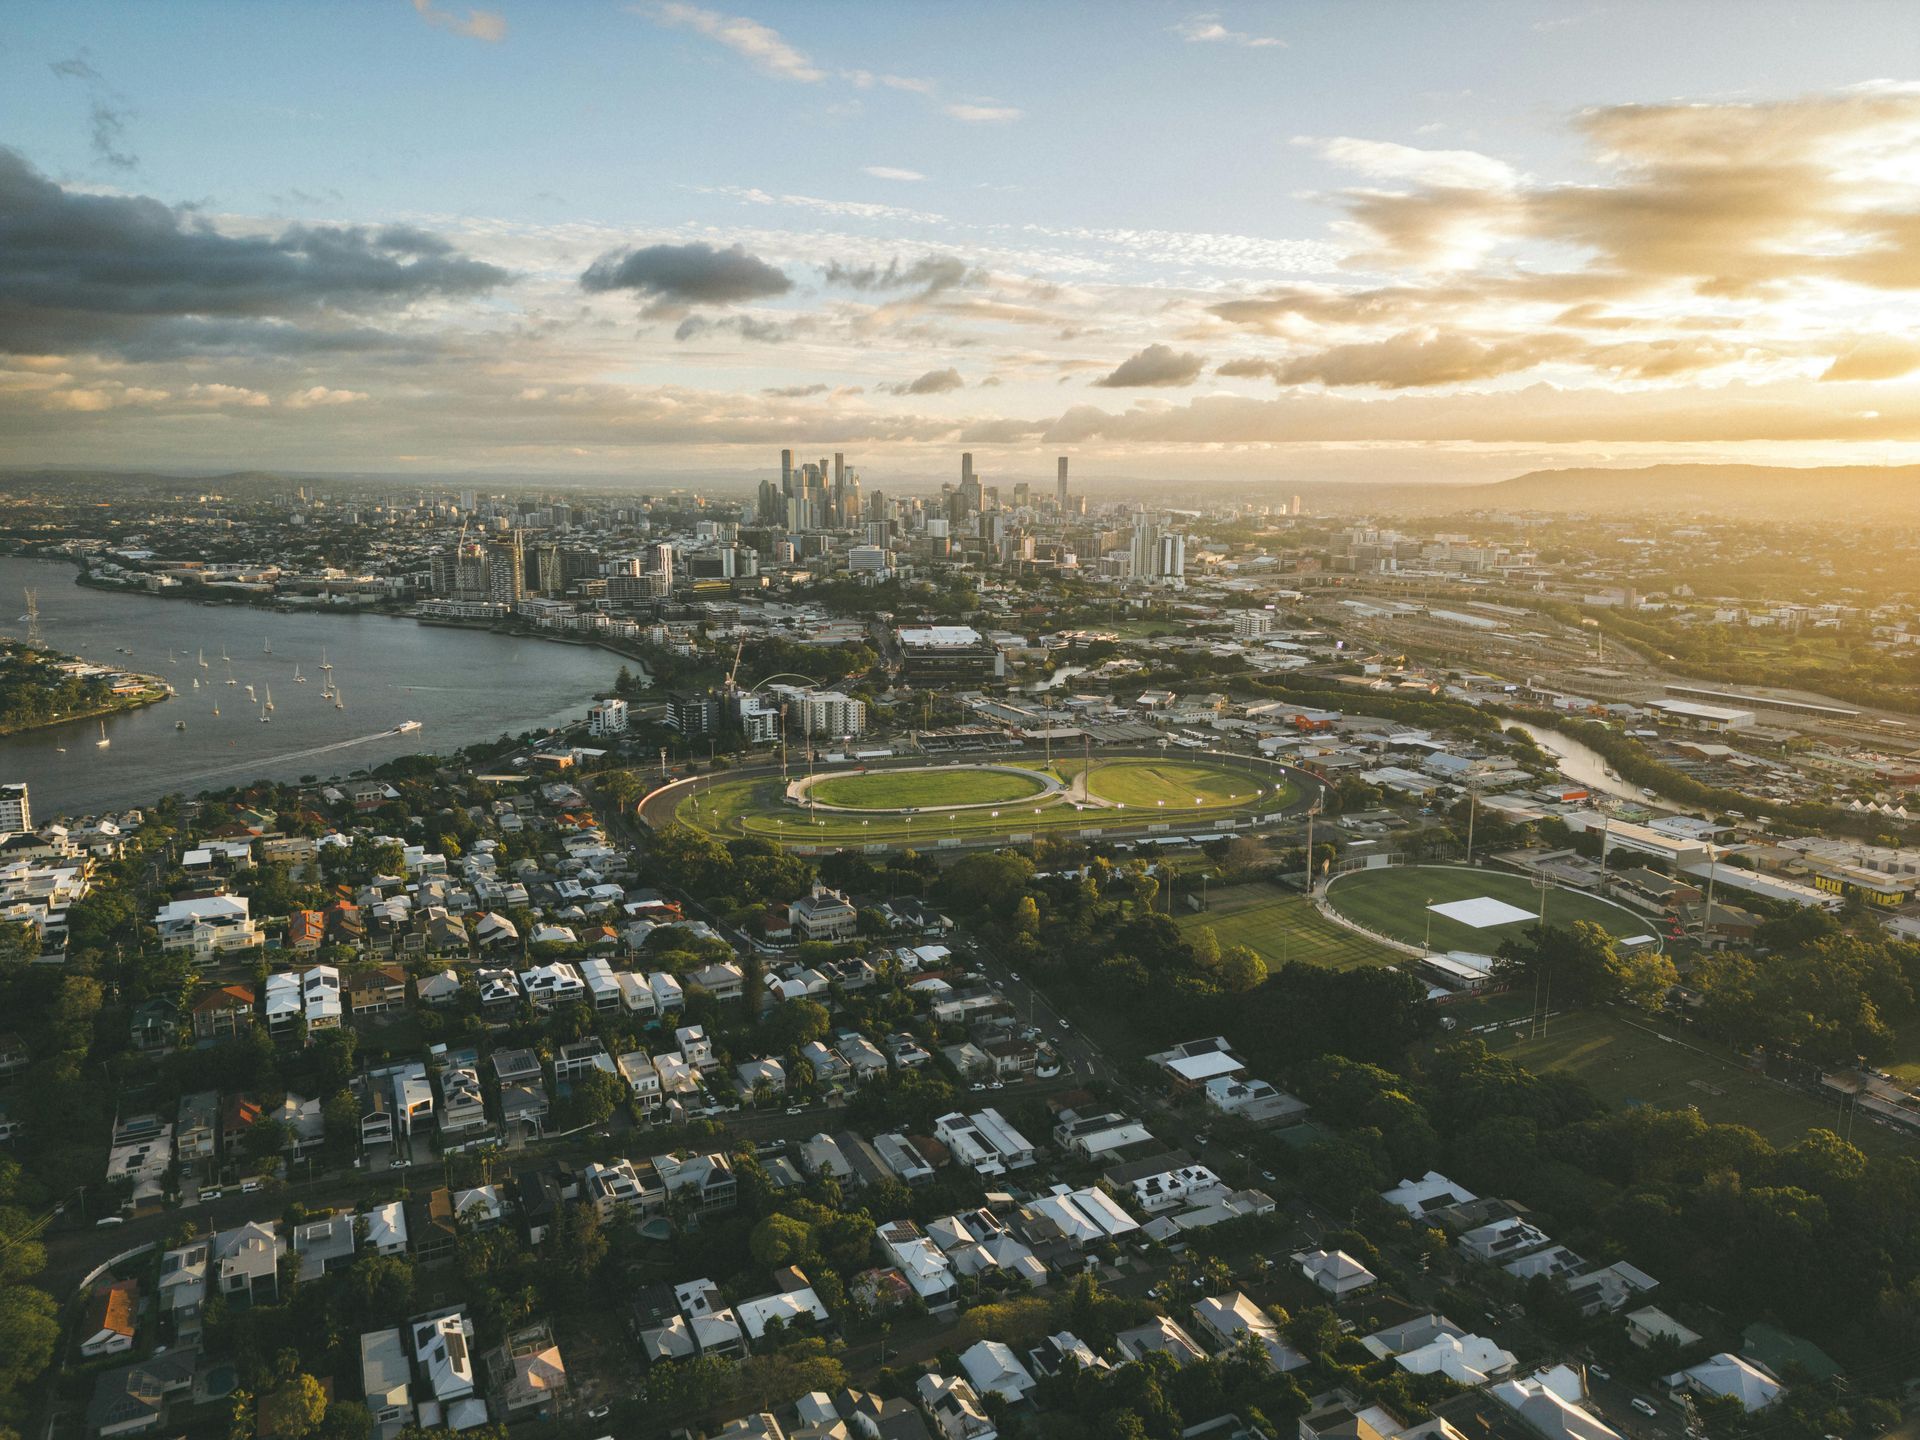
From consultants around Brisbane Technology Park to tradies, transport operators and the restaurant and retail owners of Sunnybank and Macgregor, the Southside runs on small business. We work with sole traders, contractors, freelancers and business owners every day.
Different lenders apply meaningfully different rules to the same set of financials. Gundeep can walk through yours in English, Punjabi or Hindi, and tell you which lender gives you the strongest borrowing capacity.
Book a free chat to find out more.
Brisbane Southside mortgage broker reviews
“Evergreen Loan solutions have been very helpful throughout our journey. I want to thanks Gundeep for the support all through this journey of buying a house.
Evergreen home solutions has always been very professional and always guided us to realise our dream house."
Monika Goel
June 2026
★★★★★
5.0 star Google reviews
FAQs
What documents do self-employed borrowers need?
Most lenders want two years of personal and business tax returns, financial statements and notices of assessment, plus ID and bank statements. Where your returns are not lodged or do not reflect current trading, low doc options can use BAS statements, business bank statements or an accountant's declaration instead, usually at a slightly higher rate. Learn more about low doc home loans.
Can I get a home loan with less than two years of trading?
Yes, it is still possible. A smaller group of lenders will consider one year of trading, or less if you worked in the same industry beforehand, using alternative income evidence such as BAS or an accountant's letter. Pricing and deposit requirements vary between them. We match your history to the lenders whose policy fits, rather than lodging with a bank likely to decline.
Will lenders use my best year or an average?
It depends on the lender. Some average your last two years, some use the lower year, and others lean on the most recent year if income is rising. That difference matters a lot when your business is growing. Some lenders also add back items like depreciation and one-off expenses. We find the lender whose method gives you the strongest result.
What if the big banks have said no?
A decline from one bank is not a decline from the market. Non-bank and specialist lenders on our panel assess self-employed income on different rules, and some accept fewer documents or shorter trading history. We review why you were declined, check your credit file and choose a lender that suits your situation before lodging, so you do not stack up more enquiries.
What are add-backs for self-employed income?
Add-backs are expenses in your tax return that some lenders add back to your income because they are not ongoing costs, such as depreciation, interest on loans being refinanced or one-off expenses. Not every lender accepts the same add-backs. Used correctly, they can noticeably increase how much you can borrow, so we review your financials with this in mind.
Is a low doc loan more expensive?
Usually a little. Low doc loans often carry a slightly higher rate and may need a larger deposit because the lender relies on alternative income evidence. The gap has narrowed over time, and once your tax returns are up to date you can often refinance to a full doc loan. We show you the cost difference so you can decide.




